

 Wealth Insights
|
September 2, 2026
A Rally Fueled by Broadening Earnings Growth
Written by Shan Gao, CFAStrong Earnings are Supporting Higher Markets
Global equity markets have reached new highs in 2026. The MSCI All Country World Index (ACWI) returned approximately 11% in the first six months of the year, well above its historical average return of approximately 5% for six‑month periods since 1990.
What makes this rally particularly interesting is not simply the strength of returns, but what is driving them. Unlike some previous market rallies, where valuations expanded ahead of fundamentals, the current advance has been supported by exceptionally strong corporate earnings. Earnings expectations have risen across the US, Europe and emerging markets, supporting higher equity prices, while keeping valuations in check.
This environment has been particularly supportive of our investment approach. Rather than relying on a single market theme, our portfolios are built around global diversification, attractive valuations, exposure to smaller companies and an emphasis on underlying business quality.
Profitability is Improving Across Regions
Corporate profitability has improved across major markets over the past several years. In emerging markets, aggregate net margins have risen from below 20% a few years ago to roughly 28% as of Q2 2026. Developed markets have also experienced moderate improvements in net profit margins.
While it is difficult to isolate the exact contribution from AI, companies across a wide range of industries are increasingly adopting automation, data analytics and productivity‑enhancing technologies. Combined with resilient economic activity, these have provided a supportive backdrop for corporate earnings.
Chart 1: Corporate Profitability Has Improved Across Major Regions
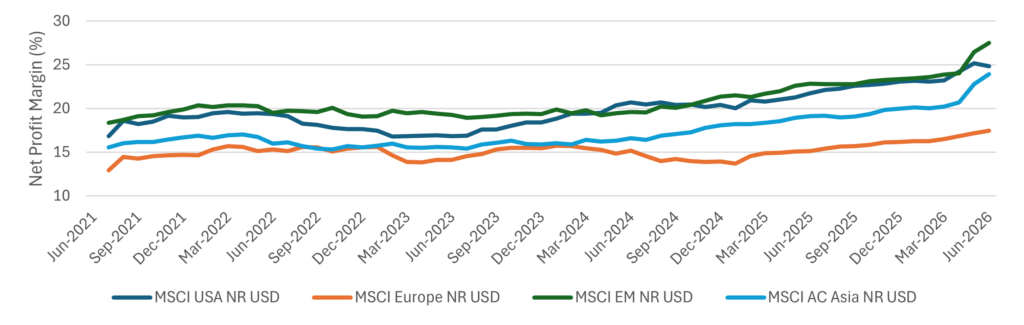
Source: Bloomberg, MSCI. As of 30 June 2026. Net profit margin represents the percentage of revenue remaining after a business has paid all expenses. The figures above refer to the past, past performance is not a reliable indicator of future results
Earnings Growth is Becoming More Broad-Based
Earnings growth is no longer concentrated in a small group of mega-cap technology companies.
In the US, Q2 earnings growth is tracking at approximately 48%, while fullyear 2026 earnings growth expectations for the S&P 500 now exceed 30%. Earning revisions have been positive across a wide range of sectors, with the majority of sectors expected to deliver positive earnings growth according to FactSet[1].
Europe is telling a similar story. With approximately 83% of STOXX 600 companies having reported Q2 results, aggregate reported earnings growth is tracking close to 20%[2], one of the strongest reporting seasons in recent years. Emerging markets are also delivering robust earnings growth, supported by its growing participation in the global AI supply chain, stronger profitability and improving economic conditions.
Chart 2: Global Equity Return Decomposition
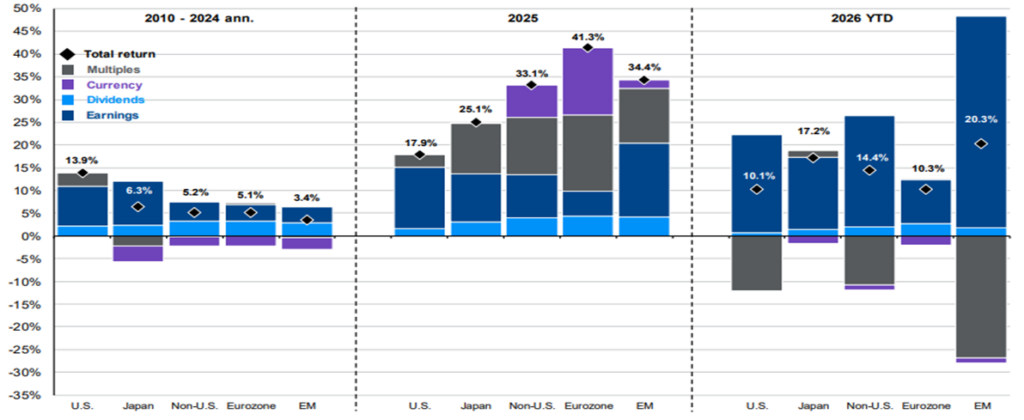
Source: FactSet, MSCI, Standard & Poor’s, J.P. Morgan Asset Management., Guide to the Markets – US, are as of 31/07/2026. All return values are MSCI Gross Index data, except the US, which is the S&P 500. Non-U.S . is MSCI AC World ex USA Index. Multiple expansion is based on the forward P/E ratio, and EPS growth outlook is based on next 12months earnings estimates. Chart is for illustrative purposes only. Past performance is no guarantee of future results.
As earnings broaden across sectors and regions, investment opportunities are becoming less concentrated and more widely distributed across global markets.
The Next Phase of the AI Story
Artificial intelligence (AI) remains one of the most important investment themes of the decade. Adoption continues to accelerate and companies are investing heavily in the infrastructure required to support it.
At the start of 2026, consensus estimates suggested that the five largest hyperscalers would collectively spend around $602 billion on capital expenditure during the year[3]. By mid-year, Bloomberg estimates had increased to more than $798 billion, which is 80% above an already record level of spending in 2025.
Chart 3: The Five Largest Hyperscalers’ AI Capex
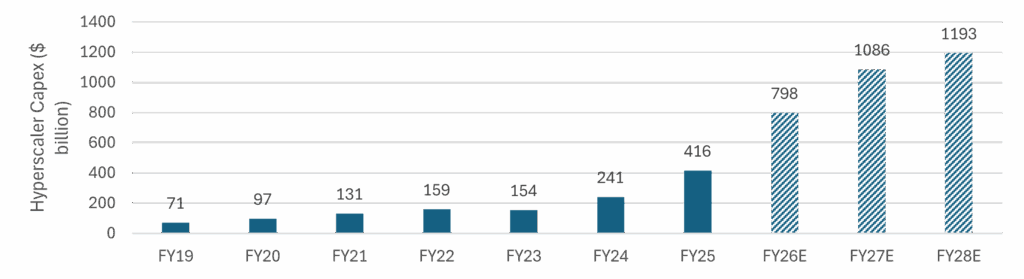
Source : Bloomberg, J.P. Morgan Asset Management. Five largest hyperscalers include Amazon, Alphabet, Microsoft, Meta, and Oracle. Data for 2026 , 2027 and 2028 reflect consensus estimates. Capex shown is company total. *Hyperscalers are the large cloud computing companies that own and operate data centers with horizontally linked servers that, along with cooling and data storage capabilities, enable them to house and operate AI workloads. Guide to the Markets – U.S . Data are as of August 20 , 2026.
While this spending has fuelled growth across AI supply chains, it has also reshaped the financial profiles of the companies funding the buildout. Businesses that once returned substantial capital to shareholders through dividends and buybacks are now directing increasing portions of that cash flow towards AI infrastructure.
As a result, FactSet projects aggregate free cash flow for the five largest hyperscalers to fall from approximately $234 billion in 2025 to around zero or slightly negative in 2026, as AI-related capex absorbs almost all operating cash flow[4].
Chart 4: The Hyperscaler Cash Flow Squeeze
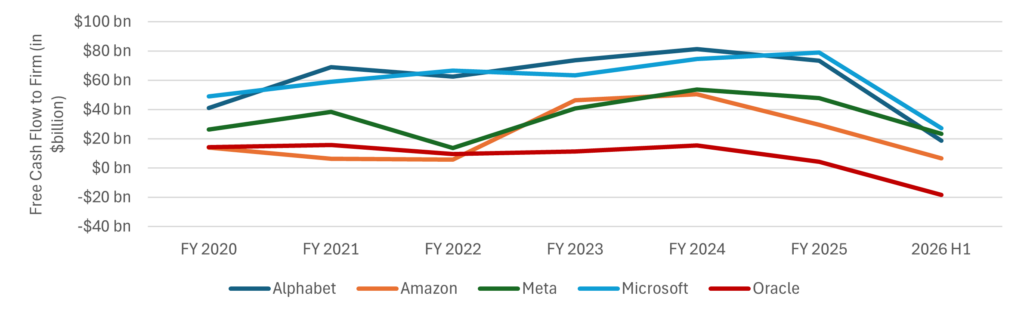
Source: Bloomberg, as of 30 June 2026
As AI investment reaches this scale, investors are becoming increasingly focused on whether and when this investment translates into sustainable earnings growth. Markets are increasingly rewarding companies with a clear path from investment to earnings, while scrutinising those where the payoff remains further out on the horizon. This contributed to the valuation reset across parts of the technology sector during the summer.
Opportunities Beyond the Largest Companies
Smaller companies are one area where we continue to see attractive opportunities.
Historically, small-cap companies tend to benefit when earnings growth broadens and business confidence improves. There are increasing signs that those conditions are beginning to emerge.
The US National Federation of Independent Business (NFIB) Small Business Optimism Index rose 2.4 points in July to 99.8, reaching its highest level since August 2025 and beating the 52-year historical average of 98[5]. While sentiment indicators are not direct measures of fundamentals, they can provide useful signals about expansion and hiring plans.
At the same time, many smaller businesses are gaining access to productivity tools previously available only to large enterprises. While AI may dominate headlines through the activities of hyperscalers, many of the benefits could ultimately accrue to companies applying these technologies to improve efficiency and profitability. Whether through automation, software tools or AI-enabled services, technology is lowering barriers and helping firms operate more efficiently. Combined with attractive valuations relative to large-cap peers, this creates an increasingly compelling opportunity set in our view.
Positioning for the Next Phase of Growth
Our recent outperformance reflects several developments that align well with our long‑term investment philosophy.
Our portfolio remains globally diversified with meaningful exposure to international equities, value stocks and smaller companies. We systematically target securities with higher expected returns, focusing on attractive valuations and exposure to smaller companies, while using profitability to distinguish temporarily undervalued businesses from those facing structural deterioration.
The broadening of earnings growth across regions and sectors has been particularly supportive of this approach. As market leadership becomes less concentrated, opportunities are becoming more widely distributed across the global economy.
Looking ahead, we remain constructive on the outlook for global equities. Earnings growth remains strong, profitability continues to improve, and the benefits of innovation are beginning to spread beyond the companies building AI infrastructure to the businesses using it to improve productivity and profitability. (See also our article: Positioning for the Next Wave of Innovation). That is the environment our investment philosophy was designed to navigate. We believe our portfolios are well positioned to participate as leadership evolves, while diversification helps manage the risks that inevitably accompany changing market conditions.
The Legal Stuff
- The information contained herein is subject to copyright with all rights reserved. The document may not be copied, forwarded or otherwise distributed, in whole or in part, to any other party without our written consent.
- Nothing in this document constitutes investment, tax or any other type of advice and should not be construed as such.
- MASECO is not a tax specialist and we recommend that anyone considering investing seeks their own tax advice.
- The views expressed in this article do not necessarily reflect the views of MASECO as a whole or any part thereof.
- This document is provided for information purposes only and is not intended to be relied upon as a forecast, research or investment advice.
- This document does not constitute a recommendation, offer or solicitation to buy or sell any products or to adopt an investment strategy.
Risk Warnings:
- All investments involve risk and may lose value. The value of your investment can go down depending upon market conditions and you may not get back the original amount invested.
- Your capital is always at risk.
- Fluctuation in currency exchange rates may cause the value of an investment and/or a portfolio to go up or down.
Performance:
- Past performance is not a reliable indicator of future results.
- No assurance or guarantee can be given that any target return will be achieved.
- Illustrations of potential risk or return are illustrative only and do not necessarily reflect possible actual maximum loss or gain.
MASECO LLP is authorised and regulated by the Financial Conduct Authority for the conduct of investment business in the UK and is registered with the US Securities and Exchange Commission as a Registered Investment Advisor.
[1] FactSet, S&P 500 Earnings Season Update, 31/07/2026
[2] FactSet, STOXX 600: Europe Delivers One of Its Strongest Q2 Earnings Growth Rates in Years, Led by Energy, 14/08/2026
[3] CreditSights, Hyperscaler Capex 2026 Estimates, 10 November 2025
[4] FactSet, Hyperscalers Tap External Financing As AI Capex Outruns Cash Flow, 23 July 2026
[5] The Wall Street Journal, U.S. Small Business Confidence Rose Last Month, 11/08/2026. NFIB Index data as of July 2026.